


If you are about to spend weeks or months abroad, the question is not whether you can find cheap travel medical insurance. It is whether the plan you pick will still pay when the bill is real, and the differences hide in five places: the pre-existing condition rule, the deductible, the age cap, the maximum trip length and what happens if you need care in the United States. I put this guide together for the store owners and remote workers who read Ecommerce Paradise. A lot of them are building a high-ticket dropshipping business from a laptop in another country.
Everything below is as of October 7, 2026, and it comes from the insurers’ own plan pages, policy FAQs and a few independent sources. I have not bought these policies, filed claims or tested the apps for this piece, so treat this as a research summary and confirm every number on the quote page before you pay. Where two pages from the same company disagree, I say so.
This is general information, not personalized insurance, medical or financial advice, and I am not a licensed insurance agent or advisor. I will not tell you which policy you must buy. I will lay out limits, exclusions and tradeoffs so you can decide.
Disclosure: I may earn a commission if you sign up through my SafetyWing link, at no extra cost to you. It does not change what the policy documents say, and I point out where Trawick, Seven Corners, Allianz or another insurer fits better.
| Plan | Type | Medical limit | Deductible | Pre-existing conditions | Age rules | Length of cover |
|---|---|---|---|---|---|---|
| SafetyWing Nomad Insurance (Essential and Complete) | Essential: travel medical. Complete: full health plan | Essential $250,000. Complete $1.5 million per policy year | None on either plan | Excluded on Essential (180-day lookback on the current version). Complete uses a stricter definition | Essential up to 69. Complete ages 18 to 64, renewable for life if bought before 64 | Essential up to 364 days. Complete is a 12-month commitment |
| Trawick Safe Travels Outbound and International | Travel medical | $50,000 to $500,000 (Outbound), $50,000 to $1,000,000 (International) | $0 to $5,000 on International | Excluded, with a capped unexpected recurrence benefit on International (up to $2,500, through age 69) | Overall age cap not shown on the pages I could read | 5 to 180 days (Outbound), 5 to 364 days (International) |
| IMG Patriot (Lite, Plus, Platinum) | Travel medical | Listed on IMG’s compare page when I first read it as $50,000 to $1,000,000 (Lite and Plus) and $2,000,000 to $8,000,000 (Platinum). Confirm on the quote page | Not shown on the pages I could read | Excluded per IMG’s disclaimer | Not shown on the pages I could read | Not shown on the pages I could read |
| Seven Corners Travel Medical | Travel medical (limited benefit, secondary) | $1,000,000 up to age 64, $100,000 ages 65 to 79, $10,000 at 80 and over | $0, $100, $250, $500 or $1,000 | Acute onset benefit only | Medical limit drops with age | 5 to 364 days |
| Allianz OneTrip Emergency Medical | Medical plus travel mishaps, no trip cancellation | $50,000 | Not shown on the page I could read | Excluded unless a waiver applies: buy within 14 days of your first trip payment, insure the full non-refundable trip cost and be medically able to travel when you buy (US residents only) | No age limit stated | No maximum stated |
| World Nomads (US plans) | Trip insurance with medical | $125,000 Standard, $150,000 Explorer, $250,000 Epic | Not shown on the page I could read | Excluded on Standard. Explorer and Epic offer a waiver if bought in a time-sensitive window and you are healthy enough to travel | Not shown on the page I could read | Not shown on the page I could read |
| Genki Traveler | Monthly travel medical | Up to €1,000,000 | €50 per case, none for inpatient stays | Excluded if symptoms, diagnosis or treatment in the prior year | Up to 69 at start | Up to 12 months |
| Cigna Global (Silver, Gold, Platinum) | International health insurance | Annual maximum of $1,000,000 (Silver), $2,000,000 (Gold) and listed as paid in full (Platinum) | Chosen when you build the plan | Depends on underwriting | From 18, no upper age limit | Annual, renewable |
Cover a Hospital Stay Abroad Without a Deductible or a Return Date
SafetyWing’s Nomad Insurance Essential lists a $250,000 medical limit, no deductible, ages up to 69 and coverage for up to 364 days that you can buy after you have left home.
The Short Answer: Which Plan Fits Which Trip
For a store owner who will be abroad for months with no fixed return date, I would start with SafetyWing Nomad Insurance and compare it to Genki. Both sell recurring plans you can start after you have already left, neither charges a deductible on hospital stays, and both cap the buying age at 69 for the travel medical version.
For a two-week trip with a clear return date, Seven Corners and Allianz are the more traditional picks. Seven Corners lists up to $1,000,000 of medical cover and $500,000 for evacuation on its plan for US residents going abroad, and Allianz sells an emergency medical plan with up to $50,000 of medical and $250,000 for evacuation.
If you are moving abroad for good, a travel medical plan is the wrong category. SafetyWing’s Complete plan and Cigna Global are built as health insurance, which is a different product with different rules, and I explain the split in the next section.
Travel Medical vs Trip Insurance vs Health Insurance
These three products get mixed up constantly, and mixing them up is how people end up with a cancellation policy when they needed a hospital policy. The National Association of Insurance Commissioners says travel insurance covers risks such as lost luggage, trip cancellation and delays, while travel medical insurance offers secondary health and accident cover in case of illness or injury while traveling.
Travel medical insurance
This pays for illness or injury abroad and usually includes evacuation and repatriation. It is the category built around a large medical and evacuation limit for a defined stay, and plans such as Seven Corners and Trawick advertise limits from $50,000 up to $1,000,000. Seven Corners describes its plan as secondary (excess) coverage and a limited benefit policy, not comprehensive health insurance.
Trip insurance with medical cover
This bundles trip cancellation, delay and baggage benefits with an emergency medical limit, and the medical part is often smaller. World Nomads’ US plans list $125,000, $150,000 and $250,000 of medical cover by plan, and Allianz’s OneTrip Premier lists $75,000 of medical against up to $200,000 of trip cancellation. If protecting prepaid flights matters more than a big medical limit, my guide to travel insurance for international trips covers that side.
International health insurance
This is a full health plan for people living abroad, built for ongoing care and not just emergencies. Cigna’s own page draws the same line: health insurance covers long-term care and generally pre-existing conditions, while travel insurance is short-term. SafetyWing’s Complete plan sits in the health insurance category too, which is why its price is closer to $177.50 a month than $62.72 every four weeks.
Why your home plan probably is not enough
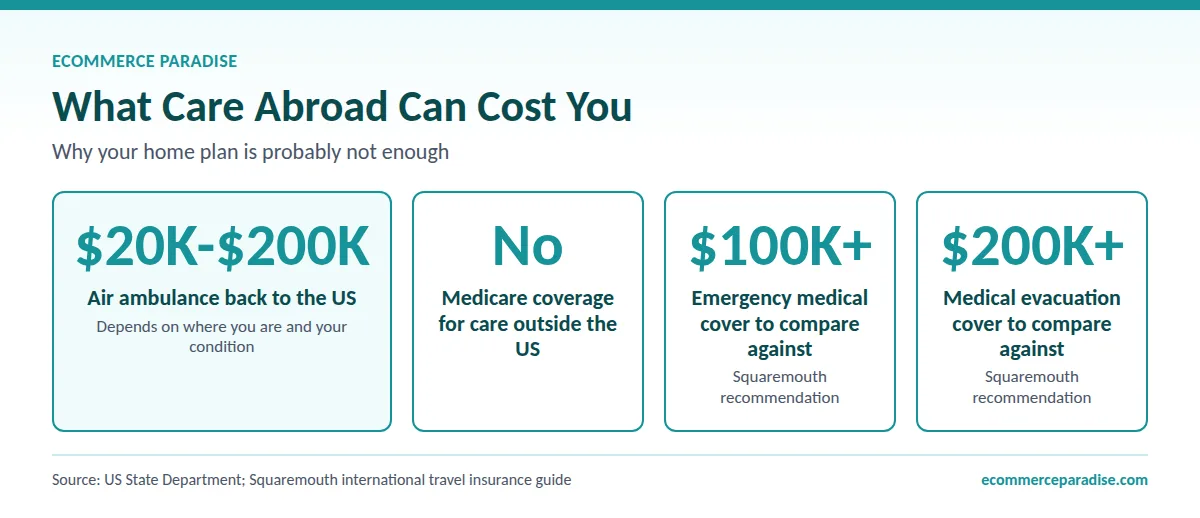
The US State Department says plainly that Medicare does not cover medical costs outside the United States. The same page says a medical evacuation by air ambulance back to the United States can cost from $20,000 to $200,000, depending on where you are and your health condition. Check your own plan’s rules for care abroad before you assume anything.
How I Picked These Eight Plans
I started with the insurers that already show up in comparisons of travel medical and international plans, then kept the ones whose own pages let me read real limits. I compared each plan on the five things that decide claims: the medical limit, the deductible, the pre-existing condition rule, the age cap and the maximum length of cover. Price matters, but most of these insurers do not publish a flat price because it depends on your age, trip length and limit.
The sources were each insurer’s plan pages and policy FAQs, the NAIC’s consumer page on travel insurance, the State Department’s health abroad page, NerdWallet’s travel insurance roundup and Squaremouth’s international travel insurance guide. I did not use user reviews to rank anything. I also could not find independent claim-denial statistics for any of these insurers, so nothing here ranks them on how often they pay.
One practical point on sizing. Squaremouth’s international travel insurance guide recommends at least $100,000 of emergency medical and at least $200,000 of medical evacuation, so compare each plan’s limits against those figures. It is a marketplace’s guideline, not a rule, so weigh it against the State Department’s $20,000 to $200,000 evacuation range.
The Eight Plans, One at a Time
1. SafetyWing Nomad Insurance (Essential and Complete)
SafetyWing Nomad Insurance is two products under one name. Essential is travel medical insurance, listed at $62.72 every four weeks for the youngest adult bracket at the time of writing (the plan card says ages 18 to 39, while the age selector and FAQ start the bracket at 10), with a $250,000 overall limit, $100,000 lifetime evacuation and no deductible. Complete is full health insurance, listed at $177.50 a month for ages 18 to 39, with up to $1.5 million per policy year.
The conditions matter more than the price. Essential covers new, unexpected illness or injury, and its FAQ says it does not cover pre-existing conditions, maternity care beyond emergencies, or cancer treatment. You can buy it while you are already abroad, and cover in your home country is limited to 30 days per 90 days, or 15 if your home country is the US.
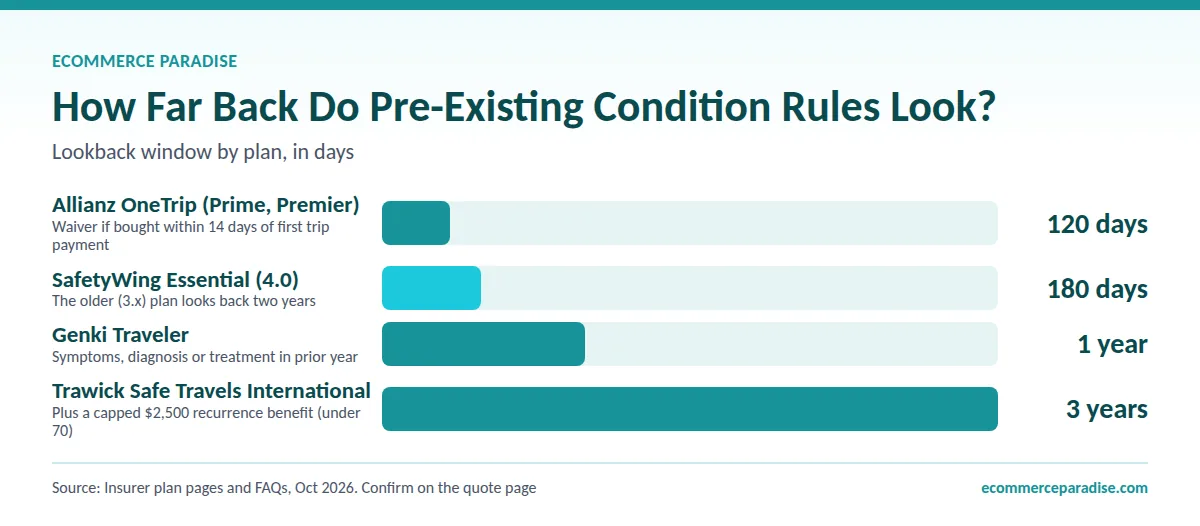
The FAQ lists two pre-existing definitions for Essential. The current 4.0 plan looks back 180 days before the start date, while the older 3.0 plan looks back two years, so check which version your certificate shows. Complete is stricter: anything treated or diagnosed in your lifetime, plus any symptoms in the last two years, counts as pre-existing. I cover both plans in more depth in my SafetyWing review.
Two sources on safetywing.com conflict on price. The plans page lists $62.72 and $177.50, while the FAQ lists $67.72 every four weeks for Essential and $161.50 a month for Complete. I used the plans page figures, but confirm the price at checkout. I would not rely on any figure in this guide for your age bracket, because SafetyWing’s prices by age come from a calculator I could not read.
2. Trawick International (Safe Travels Outbound and International)
Trawick splits its travel medical line by who you are. Safe Travels Outbound is for US citizens and residents leaving the US, with medical limits of $50,000, $100,000, $250,000 or $500,000, $500,000 for emergency medical evacuation and 5 to 180 days of cover. Its page says it is not available to anyone who has already left on their trip.
Safe Travels International is for non-US citizens and residents traveling outside their home country, excluding the US. It offers limits from $50,000 to $1,000,000, deductibles from $0 to $5,000 and 5 to 364 days of cover. Pre-existing conditions are defined with a three-year lookback, and the plan adds a capped unexpected recurrence benefit of up to $2,500 for ages up to 69. Skipping pre-certification cuts eligible medical expenses by 50 percent.
The detail worth flagging, since a lot of nomads base themselves in Bali, is that the Safe Travels Outbound page says the plan is not available for travel to or in Indonesia, along with Lebanon, Cuba, North Korea, Palestine, Syria, Iran, Sudan, Ukraine and Crimea, Belarus, Russia and other restricted countries. I did not see an Indonesia line on the International page, but I would not assume either plan works there, so confirm with Trawick before you plan around it for Southeast Asia. Trawick also publishes a longer review on this site if you want the company background.
3. IMG Patriot (Lite, Plus and Platinum)
IMG’s travel medical line is the Patriot series. When I first read its compare page, it listed Patriot Lite and Plus at $50,000 to $1,000,000 of medical with evacuation up to $1,000,000, and Patriot Platinum at $2,000,000 to $8,000,000 of medical with evacuation up to $8,000,000, with telehealth included on Platinum. The plan pages load their details with scripts and did not return those figures when I checked again, so treat the numbers as a starting point and confirm them on a live quote.
IMG’s own plan pages state an exclusion for pre-existing medical conditions. I could not read deductibles, age limits or maximum duration from the plan pages as they render, and I did not want to guess, so pull those from IMG’s plan documents. NerdWallet’s travel insurance roundup labels IMG best for long-term travelers, which is a reason to get a quote if your trip runs for many months.
4. Seven Corners Travel Medical
Seven Corners sells three travel medical versions: Excluding the USA for US residents, Including the USA for non-US residents, and Global for non-US residents. The Excluding the USA plan lists up to $1,000,000 of medical for travelers up to age 64, $100,000 for ages 65 to 79 and $10,000 at 80 and over, plus up to $500,000 for emergency medical evacuation.
You pick a deductible of $0, $100, $250, $500 or $1,000, and cover runs 5 to 364 days with a $5 fee for each extension. Pre-existing conditions are handled through an acute onset benefit of up to $50,000 for travelers 64 and younger and $10,000 for ages 65 to 79. It covers a first acute onset after a 72-hour waiting period if you had no change in prescription or treatment in the last 30 days, and the condition cannot be chronic or deteriorating.
The Excluding the USA plan is for US residents and is not sold in New York, and the plan is secondary coverage. Motorcycle and scooter cover needs an optional add-on, and there is a $35 cancellation fee after the effective date even if you have made no claims. That makes it a good fit for a defined trip, but read the exclusions if you ride a bike.
5. Allianz OneTrip Emergency Medical
Allianz’s OneTrip Emergency Medical plan provides benefits for emergency medical expenses and travel mishaps such as trip delays and lost luggage, without trip cancellation. It lists up to $50,000 of medical expense, a $750 cap on dental, up to $250,000 for emergency evacuation, up to $1,000 for trip delay and up to $2,000 for baggage loss. The plan is only available to US residents.
Pre-existing conditions are excluded unless a waiver applies, and the plan page lists the same waiver conditions as Prime and Premier. You must buy within 14 days of your first trip payment, insure the full non-refundable cost of your trip, be a US resident and be medically able to travel when you buy. For frequent travelers, Allianz’s AllTrips Basic lists $20,000 of medical and $100,000 for evacuation, and it excludes trips longer than 45 days. The higher OneTrip Premier plan lists $75,000, $1,000,000 for evacuation and trips up to 366 days.
6. World Nomads
World Nomads is a trip insurance product with medical cover bundled in. Its US plan page lists Standard at $125,000 of medical and $400,000 for evacuation, Explorer at $150,000 and $500,000, and Epic at $250,000 and $700,000. Its Annual plan lists up to $100,000 of medical per trip.
The main selling points are the adventure activity list and that you can buy cover while already traveling. The activity count conflicts across its own pages, 150+ on the global page and 250+ to 340+ on the US plan page, so check the list for your activity and your country of residence. World Nomads says most plans do not cover conditions that exist before you buy. Its US page says Explorer and Epic can include a pre-existing exclusion waiver if you buy within a time-sensitive window and are healthy enough to travel, and its global page says over 40 specific medical conditions may be covered depending on where you live.
7. Genki Traveler
Genki Traveler is a monthly travel medical plan with up to €1,000,000 of cover, available up to age 69 at the start. You can stay covered for up to 12 months and cancel any time after the first month. It has a €50 deductible per insurance case, with none for inpatient stays.
The fine print is where Genki differs. Cover in your home country is emergencies only for the first 6 weeks of each stay, cover in the USA and Canada is emergencies only for the first 7 days by default, and conditions with symptoms, diagnosis or treatment in the prior year are excluded. If you are already abroad with no prior cover when you start, only emergencies are covered for the first 14 days, and costs of €1,000 or more need an itemized estimate 5 days ahead or only 50 percent is reimbursed. I could not find a flat price on the pages I read, so you need to run a quote.
8. Cigna Global
Cigna Global is not travel medical insurance, and it is here because some readers shopping for it are really shopping for health insurance. Its international plans come in Silver, Gold and Platinum, are available from age 18 with no upper age limit, and list annual overall maximums of $1,000,000 for Silver and $2,000,000 for Gold, with Platinum shown as paid in full, per Cigna’s plans-in-detail page.
Outpatient care, vision and dental, and medical evacuation are optional modules, and the USA is an option you add. Cigna does not publish a flat price because you build the plan. If you are leaving your home country for good and need ongoing care, this category is the one to price next to SafetyWing Complete.
Not Sure You Qualify? Read the Exclusions Before You Pay
SafetyWing’s Essential FAQ spells out what is excluded: pre-existing conditions, cancer treatment and non-emergency maternity care.
Pre-Existing Conditions: Where Claims Get Denied
Almost every plan in this guide excludes pre-existing conditions, and the exceptions are narrow. The NAIC lists pre-existing conditions as a common exclusion in travel insurance, so check what is excluded as well as what is included.
The rules differ in ways that matter. SafetyWing Essential uses a 180-day lookback in its current plan, Genki uses one year, Allianz uses 120 days on its Prime and Premier pages and ties its waiver to buying within 14 days of your first trip payment, and Seven Corners covers only the first acute onset after a 72-hour wait. NerdWallet’s roundup describes the same pattern for Travel Guard, where a waiver is included on certain plans only when you buy within 15 days of the initial trip payment, so check the trigger and the date.
The practical lesson is that a plan for a trip you have not paid for yet is different from a plan bought the week before you leave. If you manage a condition, ask the insurer in writing how it defines the lookback, and keep your prescriptions and doctor’s notes.
US Coverage and Home-Country Rules
US coverage is the exclusion most people discover too late. SafetyWing Essential offers a US add-on that carries a $100 copay per emergency room visit and a $50 copay per urgent care visit. It is not available to US citizens or residents, and cover in your home country is capped, so a US citizen’s trip home to the US is the weak spot.
SafetyWing Complete includes up to 30 days of emergency cover in the US by default, and a Hong Kong, Singapore and US add-on extends that for up to six months. US citizens can buy Complete only if they live outside the US at least 6 months a year. SafetyWing also lists countries whose residents it cannot cover for Complete, including the USA and its territories, Canada, Portugal and the United Arab Emirates.
Other plans split the same problem differently. Seven Corners sells a separate plan for trips that include the USA for non-US residents, Trawick’s International plan is written for non-US citizens traveling outside their home country, with a separate inbound plan for the USA, and Genki limits cover in the USA and Canada to emergencies for the first 7 days by default. If you are a US citizen who flies home a few times a year, price the home visits as a separate line item, not an afterthought.
Age Limits and Trip Length
Age caps are a hard stop on some plans and a pricing change on others. SafetyWing lets you buy Essential up to age 69. Complete is available from 18 to 64, and if you buy it before 64 you can keep renewing it for life.
Genki caps buying at 69. Trawick’s International page limits its unexpected recurrence benefit to ages up to 69 and trims some cardiac limits from 70, and I could not read an overall age cap for either Trawick plan. Seven Corners keeps selling past 65 but its medical limit falls to $100,000 for ages 65 to 79 and $10,000 at 80 and over, which is a big drop from $1,000,000. Cigna Global lists no upper age limit.
Trip length works the same way. SafetyWing Essential runs up to 364 days at a time, and its FAQ says the pre-existing lookback no longer applies to new illnesses after 364 consecutive days of cover. Trawick Outbound stops at 180 days, Seven Corners and Trawick International stop at 364, Genki at 12 months, and Allianz’s AllTrips Basic excludes trips longer than 45 days. If your stay might stretch, pick the plan whose ceiling is above your worst case.
What the Plans Cost When You Do the Math
Here is my own arithmetic on the SafetyWing prices from the plans page, for ages 18 to 39. Essential at $62.72 every four weeks is about $815 for 364 days, which is 13 four-week periods.
Complete at $177.50 a month is $2,130 over 12 months, and SafetyWing’s FAQ lists a 10 percent reduction for paying annually, which would be about $1,917. Complete is a 12-month commitment. SafetyWing’s FAQ says you cannot cancel mid-year without a qualifying life event, it lets you request cancellation within the first 15 days of cover or at renewal, and it also mentions a refund of up to 65 percent of unused cover on cancellation, so read the cancellation terms before you pay.
For the other insurers I do not have a published flat price, so I will not invent one. Squaremouth says comprehensive travel insurance for trips abroad averages about $30 a day and that medical-only cover costs less, and the NAIC says trip insurance typically costs 5% to 10% of the trip price. Those are trip insurance benchmarks, not travel medical quotes, so use them only as a sanity check and get live quotes for your ages and dates.
Mistakes That Cost People Their Claim
The insurer’s own rules usually decide a claim, not the hospital bill. Four patterns repeat across these policies.
Skipping pre-approval
Several plans cut your payout if you do not tell them first. SafetyWing Complete requires pre-approval for listed procedures over $500, and says you may get back 30 percent less if you skip it. Genki wants an estimate 5 days ahead for costs of €1,000 or more, and Trawick International reduces eligible expenses by 50 percent without pre-certification.
Assuming scooters are covered
This one matters in Southeast Asia. SafetyWing sells an adventure sports add-on at $10 per four weeks on subscription plans, Seven Corners requires an optional add-on for motorcycle and scooter cover, and Genki says small scooters are covered even without a local license. Ask each insurer for the wording on your bike size and your license.
Letting the plan lapse between trips
Every plan here excludes pre-existing conditions through a lookback, so a problem that starts during a gap in cover can become an excluded condition on the next policy. SafetyWing’s FAQ says the lookback stops applying to new illnesses after 364 consecutive days of cover, which is one reason to avoid gaps on a long trip.
Buying after you already need it
Genki and SafetyWing let you buy while already abroad, but Genki limits you to emergencies for the first 14 days if you had no prior cover, and Trawick Outbound must be bought before leaving the US. Buy before the problem exists, not after it.
What This Means for a Store Owner Working From Abroad
Plenty of store owners base themselves in Bali, so the Indonesia exclusion on Trawick and the scooter rules are not abstract. If your healthcare plan for Bali or anywhere else relies on a single policy, check that your destination, your bike and your activities are all named in the wording.
If your store runs through an LLC, whether you can deduct premiums depends on your structure and country, and I am not giving tax advice here. Ask a CPA once your business entity and bank accounts are set up. Keep the receipts either way.
Many owners also travel for work, to trade shows or on trips to meet suppliers. If you do that, my supplier guide covers what to line up before you fly, and a short travel medical policy should be on that checklist. If you are still deciding what to sell from the road, my high-ticket niches list is where I would start.
If you want help building a store you can run from anywhere, the done-for-you store build is how my team does it.
Owners who want to build it themselves can use 1-on-1 coaching. The free mini course is the place to start.
For the nomad side of this decision, read how nomad insurance differs from travel insurance.
My Verdict on the Best Travel Medical Insurance for 2026
For long trips with no fixed return date, my pick from the research is SafetyWing Nomad Insurance. It lists no deductible, a $250,000 limit on Essential, ages up to 69, four-week billing and the ability to buy after you leave, and the Complete plan is full health insurance for people who are not returning home. The downsides are real: no pre-existing cover on Essential, a US add-on that US citizens cannot buy, conflicting prices across its pages and a 12-month commitment on Complete.
For a single trip with a return date, I would price Seven Corners and Allianz first, because the limits are large and the policies are easy to match to dates. For adventure-heavy trips, compare World Nomads and Genki on the activity list. For people moving abroad for good, compare SafetyWing Complete and Cigna Global as health insurance, not travel medical.
Whatever you pick, read the exclusions list before the benefit list, confirm each number on the quote page, and keep the policy documents offline. This is a summary of published terms, not a recommendation to buy any specific policy.
Ready to Lock In Medical Cover Before Your Flight?
SafetyWing lists no deductible, a $250,000 Essential limit, $100,000 lifetime evacuation and a plan that auto-extends every 28 days, but pre-existing conditions are excluded, so check your history first.
Frequently Asked Questions
What is the best travel medical insurance for a long trip abroad?
For open-ended trips, SafetyWing Nomad Insurance and Genki Traveler are the monthly plans I would compare first, because both let you buy after you leave and have no deductible on hospital stays. For a fixed-date trip, Seven Corners and Allianz may fit better, so get live quotes for your ages, dates and destinations.
Is travel medical insurance the same as travel insurance?
No. The NAIC describes travel insurance as covering risks such as lost luggage, trip cancellation and delays, while travel medical insurance is secondary health and accident cover for illness or injury while traveling. Some plans, such as Allianz OneTrip Emergency Medical, combine medical with travel mishaps but leave out trip cancellation.
Does travel medical insurance cover pre-existing conditions?
Usually not, with narrow exceptions. SafetyWing Essential, Genki and IMG exclude them, Seven Corners covers only a first acute onset after a 72-hour wait, and Allianz lists a waiver on its OneTrip plans only if you buy within 14 days of your first trip payment. Read the lookback definition before you buy.
Will travel medical insurance cover me in the United States?
Often only in a limited way. SafetyWing Essential has a US add-on that is not available to US citizens or residents, SafetyWing Complete includes up to 30 days of emergency cover, and Genki limits US cover to the first 7 days by default. Trawick International is built for travel outside your home country and points USA trips to a separate inbound plan.
Can I buy travel medical insurance after I have already left home?
Sometimes. SafetyWing Essential can be bought while you are already abroad, and Genki lets you sign up while abroad with a 14-day emergency-only waiting period if you had no prior cover. Trawick Outbound must be bought before you leave the US.
Build the Store That Pays for Your Life Abroad
My team builds the high-ticket store and lines up suppliers, so you can run the business from anywhere you can plug in a laptop. Prefer to learn it yourself? Ask about coaching.
Related Articles
If you found this useful, these guides go deeper on related topics:
- Best Travel Insurance for Digital Nomads in 2026: Top 7 Plans Compared
- Digital Nomad Insurance: Complete Guide to Staying Covered in 2026
- Best Health Insurance for American Expats in 2026 (Plans Compared)
- World Nomads Review 2026: Still the Best Travel Insurance for Digital Nomads?
- Trawick International Review 2026: Is This Budget Travel Medical Insurer Worth It?

Trevor Fenner is an ecommerce entrepreneur and the founder of Ecommerce Paradise, a platform focused on helping entrepreneurs build and scale profitable high-ticket ecommerce and dropshipping businesses. With over a decade of hands-on experience, Trevor specializes in high-ticket dropshipping strategy, niche and product selection, supplier recruiting and onboarding, Google & Bing Shopping ads, ecommerce SEO, and systems-driven automation and scaling. Through Ecommerce Paradise, he provides free education via in-depth guides like How to Start High-Ticket Dropshipping, advanced training through the High-Ticket Dropshipping Masterclass, and fully done-for-you turnkey ecommerce services for entrepreneurs who want a faster, more hands-off path to growth. Trevor is known for emphasizing sustainable, real-world ecommerce models over hype-driven tactics, helping store owners build scalable, sellable, and location-independent brands.

Still deciding what to sell?
Grab the free list of 1,000+ niches that work for high-ticket dropshipping, sorted by category.
Free. Unsubscribe any time.


